Current-date valuation
For a sale, a change of use or a transfer happening now. The value is stated as at today's date.
Capital gains tax valuation in Sydney: valuer-signed reports for today's date or a date in the past. Fee and timing confirmed before we start.
Monita prepares capital gains tax valuations for Sydney property from its office at 1/261 George Street. Where an inspection is needed, we confirm at the free consultation how it will be arranged for your location.
1/261 George Street. One valuer, one process, from the first call to the final report.
Homes, units and land, through to offices, retail and industrial.
We confirm at the free consultation how it will be arranged for your location.
For a sale, a change of use or a transfer happening now. The value is stated as at today's date.
For the date of death, the date a property was first rented, or the date you bought it. We value the property as at that earlier date. This is also called a backdated or retrospective property valuation.
For owners who want to register for a valuation as at 1 July 2027. Rules change from that date, so speak to your accountant about what applies to you.
Australia's capital gains tax rules change from 1 July 2027. For property held across that date, the market value on the day can decide how your future gain is taxed, which is why many investors are planning their valuations now.
From 1 July 2027, for resident individuals, trusts and partnerships, the flat 50% CGT discount is replaced by indexing the cost base for inflation for gains that accrue after that date, so tax generally applies to the real (after-inflation) gain. Super funds, companies and eligible new residential dwellings are treated differently.
For individuals, a minimum tax of 30% can apply to the part of a capital gain that arises under the new rules. Exceptions apply, for example for eligible new residential dwellings. Your accountant will confirm whether it applies to you.
Gains that built up to 1 July 2027 are dealt with under the existing rules, and gains after that date under the new rules. The market value of the property at that date is the reference point for splitting the two.
The main residence exemption, assets acquired before 20 September 1985 (pre-CGT) and certain new residential developments have separate treatment, so please do not assume the same outcome applies to every property.
Think of 1 July 2027 as a line through the life of your investment. Growth before the line and growth after it can be taxed differently, so the value on that day determines how much sits on each side.
A well-evidenced valuation gives you and your accountant a clear, defensible number to rely on if the figure is ever questioned.
Simple illustration
Gain up to 1 July 2027
$400,000
Dealt with under the existing rules
Gain after 1 July 2027
$300,000
Dealt with under the new rules
Illustrative only, using simple round numbers. The actual treatment depends on your circumstances, the type of asset, and the final detail of the rules and transitional arrangements. Your accountant or tax adviser will work out your result.
Ask whether the 1 July 2027 market value of your property will matter for your CGT position, and whether a valuation or the alternative apportionment method that the government has proposed (not yet finalised) may suit you better.
Australian Property Institute guidance says a valuation obtained close to 1 July 2027 is more reliable and defensible than one reconstructed years later.
A valuation as at 1 July 2027 can only be completed once that date has passed and the market evidence is available. Booking a call now helps you plan, but it is not a completed future-dated valuation.
Good evidence from around the valuation date makes a valuation stronger, and is hard to rebuild years later.
The value of the asset at the time of the CGT event is central to working out your capital gain or loss.
Long-held investment property may need a market value as at 1 July 2027 to split gains between the existing and new rules.
When a home is first used to produce income, its market value at that time can be relevant to the cost base, depending on the circumstances.
The cost base is not always the value at the date of death. It can depend on when the deceased acquired the property and how it was used.
Where a property is gifted or transferred at a non-market price, market value may be substituted for the price actually paid.
If you change tax residency, a market value at that date can matter for some assets, for example shares. Australian real property generally stays within the CGT system. Ask your accountant which applies to you.
Valuations help apportion the cost base across new lots and support transfers between related parties, entities and funds.
A retrospective valuation can establish market value as at a past date when it was not recorded at the time.
A retrospective valuation assesses what a property was worth on a specific date in the past, using the market evidence and condition of the property at that time. It supports situations where tax rules look to market value rather than the price you paid.
The ATO does not require an independent valuation in every CGT situation, and a valuation does not replace tax advice. It is evidence that your accountant or tax adviser uses to work out your cost base and tax position.
What the report includes
To prepare it, we ask for the property address, the valuation date, your accountant's instructions and any historical records you hold.
This page is general information about valuations and the CGT changes, current as at November 2026, and is not taxation, legal or financial advice. The rules and transitional arrangements are detailed and can change, so please speak to your accountant or tax adviser about your own situation.
Further reading: Australian Property Institute, The CGT changes and property valuations
Hands-on valuation experience behind every report.
Independent, signed reports for owners and advisers.
Your enquiry and your valuation stay private.
Tell us the property, the valuation date and what it is for. We confirm the scope and the fee before any work begins.
We collect the records and market evidence needed for your valuation date.
A Certified Practising Valuer analyses the evidence and prepares the valuation.
A clear, signed report, delivered within the timeline we agree at the start.
A clear, signed report your accountant can work with, with the reasoning behind the figure shown.
Many CGT valuations are arranged with an accountant. CGT valuation checklist for accountants and advisers
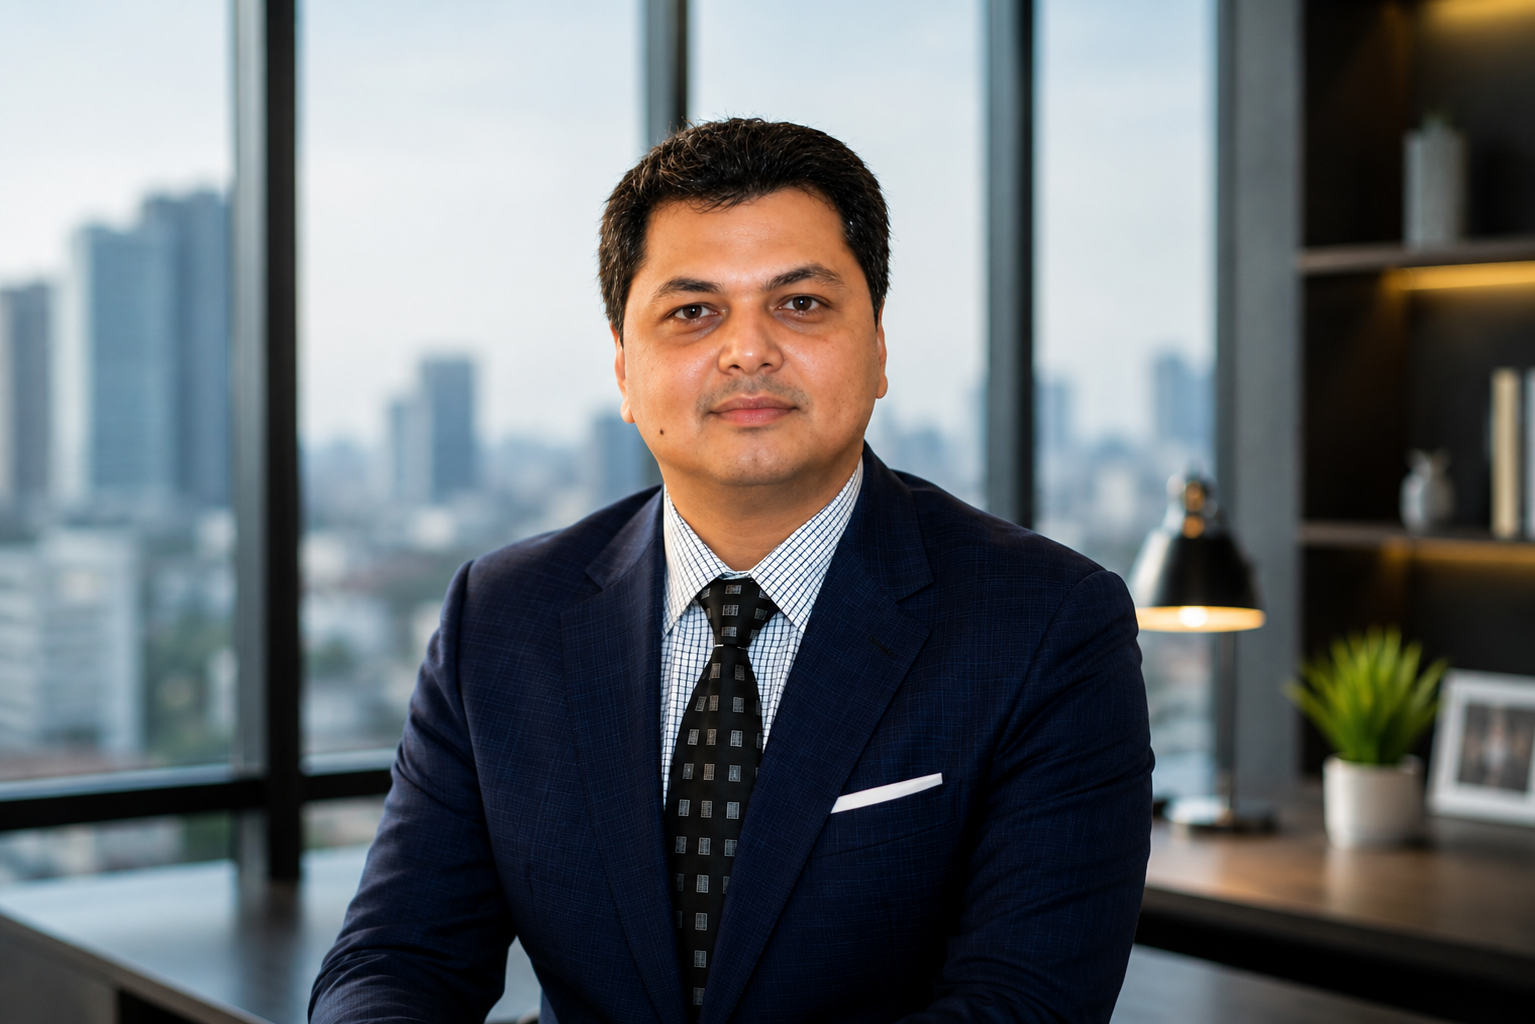
With 24 years of hands-on experience and dual Certified Practising Valuer credentials – a rare qualification spanning both Property and Plant & Machinery – Nirav brings unmatched depth to every engagement. When you work with Monita, you work directly with Nirav.
Talk to a valuerTell us about the property and the date you need the value for. A valuer will get back to you.
Mon – Fri: 8:30 am – 5:30 pm (Sydney time)
Tell us about the property and the date you need the value for.